
Mortgage Broker in Independence, KY
Experienced mortgage broker serving Independence and surrounding Kentucky communities. Find the right loan program for your situation.
Honest pricing, clear guidance, and a local team that picks up the phone — from first question to final signature.

Loan Types We Specialize In
Explore the loan programs available to Independence, KY home buyers and homeowners.
01 Purchase price
Explore a price range that fits your plans.
02 Cash to close
Consider the down payment alongside closing costs.
03 Monthly costs
Look beyond principal and interest to taxes, insurance, and other costs.
Calculator results are estimates, not a quote or loan approval.
How We Help Independence Buyers and Homeowners
- First-time buyer programs: We compare program fit against Independence property taxes, insurance, and likely escrow costs. Gather pay records, asset statements, and gift-fund details so we can identify documentation gaps before you tour homes.
- VA eligibility: We verify eligibility and prepare for appraisal concerns common with older Independence homes, acreage, septic systems, and private wells. Bring your eligibility certificate and service documentation for review.
- Self-employed or commission income: We review tax returns, current profit-and-loss records, bank statements, and commission history before you make an offer. That matters when a desirable listing near Madison Pike or Fowler Creek moves quickly.
- Condominiums and small multifamily properties: We check condominium project requirements, association finances, master insurance, leases, and rental-income documentation. Ask for association documents or existing leases as soon as the property interests you.
- Homeowner refinancing: We review your mortgage statement, escrow analysis, Kenton County tax bill, insurance declaration, and current property use. We then assess whether the refinance supports your payment, equity, or cash-flow goal.
- Fast purchases: We document your financing position before you compete in active Independence subdivisions. Expect clear coordination with your agent around appraisal timing, property condition, and financing terms that the offer can realistically support.
Financing Property Types in Independence
Near central Independence and Madison Pike, older houses may have additions, detached garages, or deferred repairs. Ask whether peeling paint, missing handrails, roof wear, or unpermitted work could affect the appraisal under condition-sensitive financing.
Fowler Creek, Sycamore Creek, and Troopers Crossing include newer subdivision properties where association dues, recorded restrictions, and tax assessments may differ from listing assumptions. Gather the association documents and current Kenton County tax bill before settling on a payment expectation.
Attached homes and condominiums near Taylor Mill Road require review beyond the unit itself. Request the association budget, master insurance policy, recorded declaration, and information about pending repairs so project eligibility is not left until late.
Along Harris Pike and Bristow Road, larger parcels can bring septic systems, private wells, barns, access easements, and agricultural use into the financing. Bring any survey, septic records, zoning information, manufactured-home title documents, foundation certification, and HUD data plate details that apply.
Properties near Banklick Creek or its tributaries deserve an early flood-zone check. Ask for the seller’s insurance information and any elevation documentation, then confirm whether flood coverage will affect qualification or the expected monthly payment.
Talk to Someone Who Knows Independence
Call before you write an offer or choose a loan structure. We will discuss the specific Independence property, review its tax, association, acreage, flood, or condition concerns, and tell you what documents to gather.
You will get a direct assessment of the financing issues that matter for that home, without pressure or promises. Bring the listing address and your questions, and we will help you plan the next move.
Frequently Asked Questions
Can I use a USDA Rural Development loan to buy a home in Independence KY?
USDA eligibility in Independence depends on the exact property address and current Rural Development maps, since some parts of Kenton County may qualify while others do not. Household income, occupancy, appraisal, and property-condition requirements also apply.
Can I finance an older Independence home that needs repairs with an FHA rehabilitation loan?
An FHA rehabilitation mortgage may combine the purchase and eligible renovation costs when an older Independence property needs more work than a standard FHA appraisal permits. The proposed repairs, contractor documentation, appraisal, and lender review must meet FHA requirements.
What mortgage works for new construction in Independence KY?
Homes in Independence subdivisions may be financed with standard purchase loans when the builder carries construction costs, while custom builds may require construction-to-permanent financing. Approval depends on the builder, plans, budget, appraisal, completion schedule, and the borrower’s qualifications.
Do higher-priced homes in Independence require a jumbo loan under Kenton County limits?
Many Independence properties can use conforming financing, but a higher-priced custom home or new build may exceed the conforming loan limit applicable to Kenton County. In that case, jumbo underwriting may require stronger credit, additional reserves, and more documentation.
Will I need flood insurance for a home near Banklick Creek in Independence?
Flood insurance may be required when the property is in a FEMA-designated high-risk flood zone and the mortgage is federally regulated or insured. A lender will use a flood-zone determination for the specific Independence address, and buyers may also want coverage outside mandatory zones.
We pride ourselves on clear communication and easy access when you need us. Answer a few quick questions and an experienced, local professional will guide you from here.
We keep you informed and supported every step of the way.
A quick call with a local advisor is the easiest first step. No pressure, no credit check.
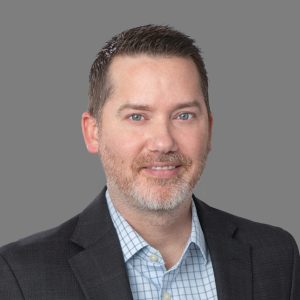
Matthew Ansert
A Louisville native; he graduated from St Xavier High School and University of Louisville with a major in Accounting. Soon after graduating he started his career as a mortgage loan originator and now has over 20 years’ experience in the industry.